The EU’s VIES service checks whether a VAT number is valid for cross-border trade using national databases. It is not a general business directory, name-to-number search engine, credit check, or guarantee that a company is active in every sense. Results and name or address details can vary by member state, and temporary service issues need a different status from an invalid number.
VISUAL LESSON
What you will learn
- 01Define what VIES validation does and does not prove.
- 02Create a reproducible number-validation record.
- 03Route invalid, unavailable, and conflicting results responsibly.
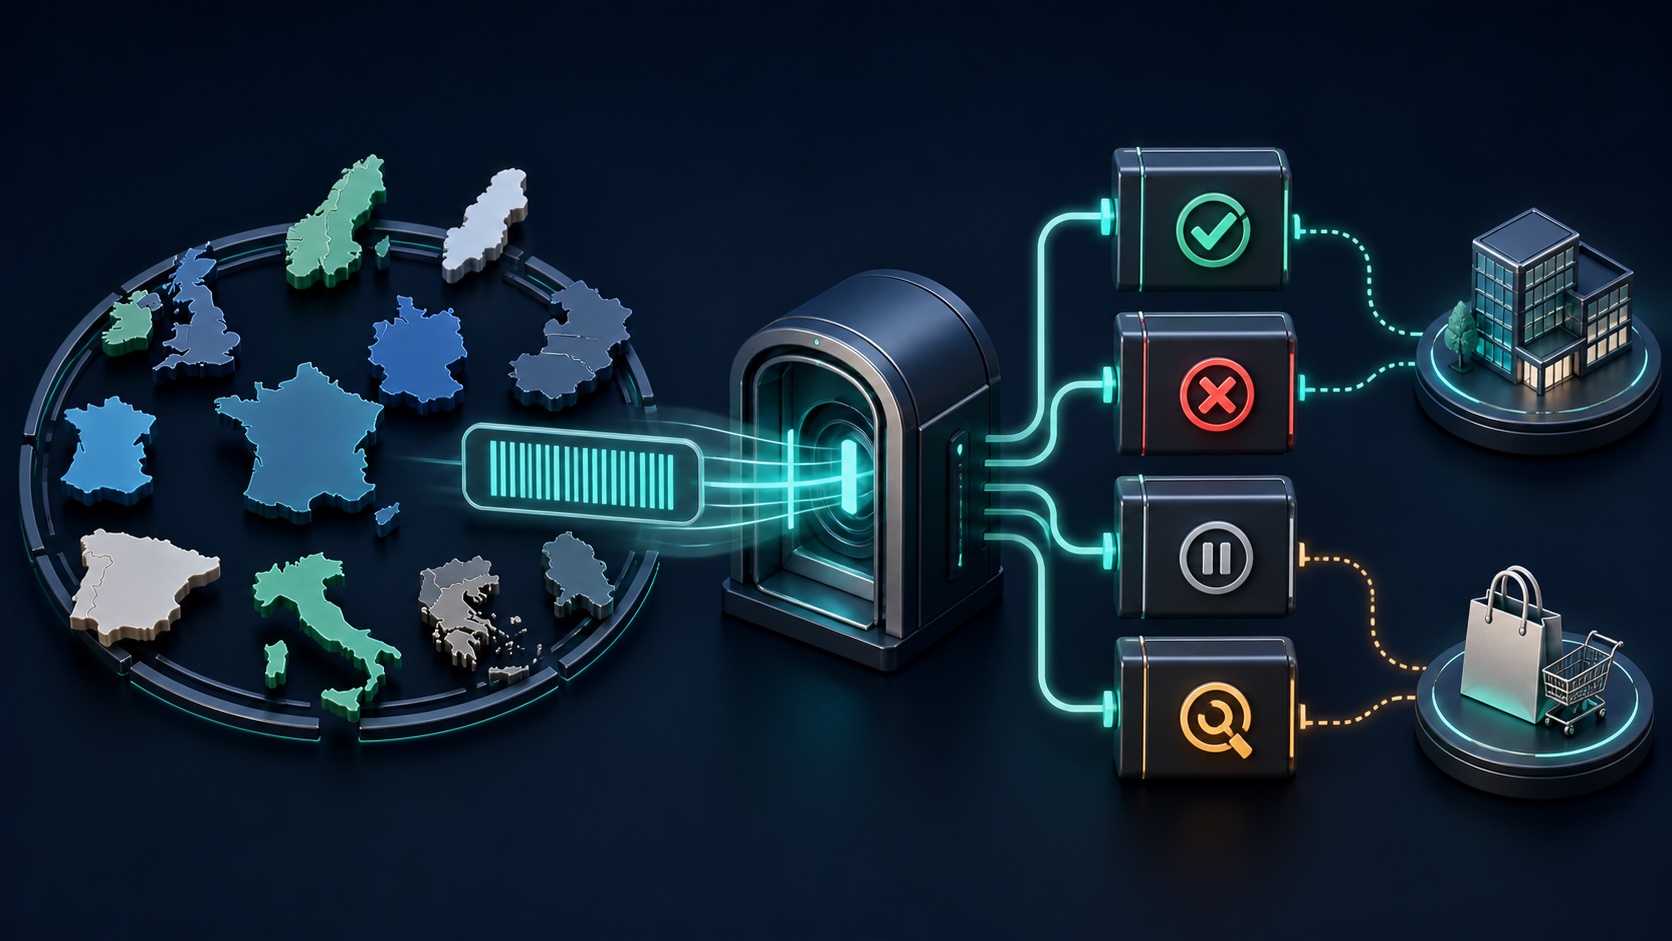
ILLUSTRATIVE WORKED EXAMPLE
Classify an illustrative 80-number validation batch
PRACTICAL INTERFACE MAP
Validate a VAT number with a narrow evidence contract
Record the supplied VAT number, member-state prefix, raw formatting, source, legal or trade name, address clues, campaign, owner, and reason for checking.
Select the issuing member state or Northern Ireland where applicable, enter the normalized number, capture valid, invalid, unavailable, corrected, name or address output, request ID, and time.
Store validation status and evidence; retry outages, investigate mismatches, and send tax consequences to the finance or tax owner.
STEP-BY-STEP LESSON
Country + supplied VAT number → VIES response → evidence record → specialist decision
THE LEAD ATLAS METHOD
Lead Atlas Data can assemble contacts specific to a customer’s European campaign, market, locations, and categories; VIES can add dated VAT-validation evidence while tax treatment and outreach suitability stay with the appropriate owners.See how custom list research works ↗Define the validation question
State the transaction, campaign, legal entity, issuing country, supplied number, source, validation reason, date requirement, owner, and what happens after each result. Decide whether this is identity support, billing setup, supplier onboarding, or another approved purpose.
VIES checks VAT-number validity for EU cross-border trade using national sources. It does not provide a complete directory, historical validation, financial health, beneficial ownership, universal operating status, marketing permission, or a substitute for tax advice.
Normalize without losing the original
Preserve the raw number exactly as received, then create a normalized copy with the correct member-state or Northern Ireland prefix and formatting required by the official validator. Store the legal name, trade name, address, domain, and original document or public source separately.
Do not guess a missing country, manufacture a number from local tax identifiers, or search names by trial and error. VIES is designed to check a known VAT number, and number structures differ across jurisdictions.
Run and capture the official check
Use the current VIES interface, select the issuing member state or Northern Ireland where applicable, enter the number, and capture the valid, invalid, corrected, unavailable, or error response; name or address when returned; requester details if used; request identifier; date, time, locale, and source URL.
National databases supply the result, so returned identity fields and availability vary. A technical outage or unavailable member-state service is not the same as an invalid number; assign a retry state and preserve the service-status evidence.
Resolve invalid or conflicting outcomes
First recheck country prefix, transcription, spacing, source date, and whether the business supplied a domestic number that is not activated for intra-EU trade. Ask the business or appropriate owner for correction when justified, retry temporary failures, and route name or address conflicts to manual review.
An invalid response does not automatically prove the company does not exist or is fraudulent. Likewise, a valid response does not prove every business claim. Tax treatment, invoicing, and exemption decisions belong to qualified tax or finance owners.
Store a dated, bounded result
Keep raw and normalized numbers, response, returned identity fields, request ID, retrieval time, source, reviewer, conflict notes, retry history, expiry or refresh policy, and the downstream decision. Limit access and retention according to the business’s governance.
Deliverable: validation-purpose statement, raw input, normalized country-number pair, VIES capture, valid/invalid/unavailable status, returned identity fields, request ID, exception queue, tax-owner decision, refresh date, limitations note, and audit trail.
Turn this lesson into a research brief.
Apply “EU VAT Numbers: Use VIES Validation Without Overclaiming Business Status” to one campaign before requesting or using a list.
- 01Market boundary
Name the locations and business categories this decision applies to.
- 02Fit evidence
Write the public signals that would make a business relevant enough to review.
- 03Exclusions
List the business types, markets, and records that should not enter the campaign.
- 04Outreach use
State who will review the list, personalize the message, and record outcomes.
THE TAKEAWAY
Validate one supplied VAT number against the correct country, store the response and date, treat invalid and unavailable outcomes differently, and ask tax or finance specialists to decide the legal consequence.OFFICIAL REFERENCES