Gross margin and markup can describe the same unit economics with different denominators. Margin divides gross profit by sales price; markup divides gross profit by cost. A product sold for $150 with $100 of cost has $50 gross profit, a 33.3% margin, and a 50% markup—not two conflicting profit amounts.
VISUAL LESSON
What you will learn
- 01Calculate gross profit, gross margin, and markup from one unit.
- 02Convert a target margin or markup into a sales price.
- 03Define cost and revenue scope before comparing results.
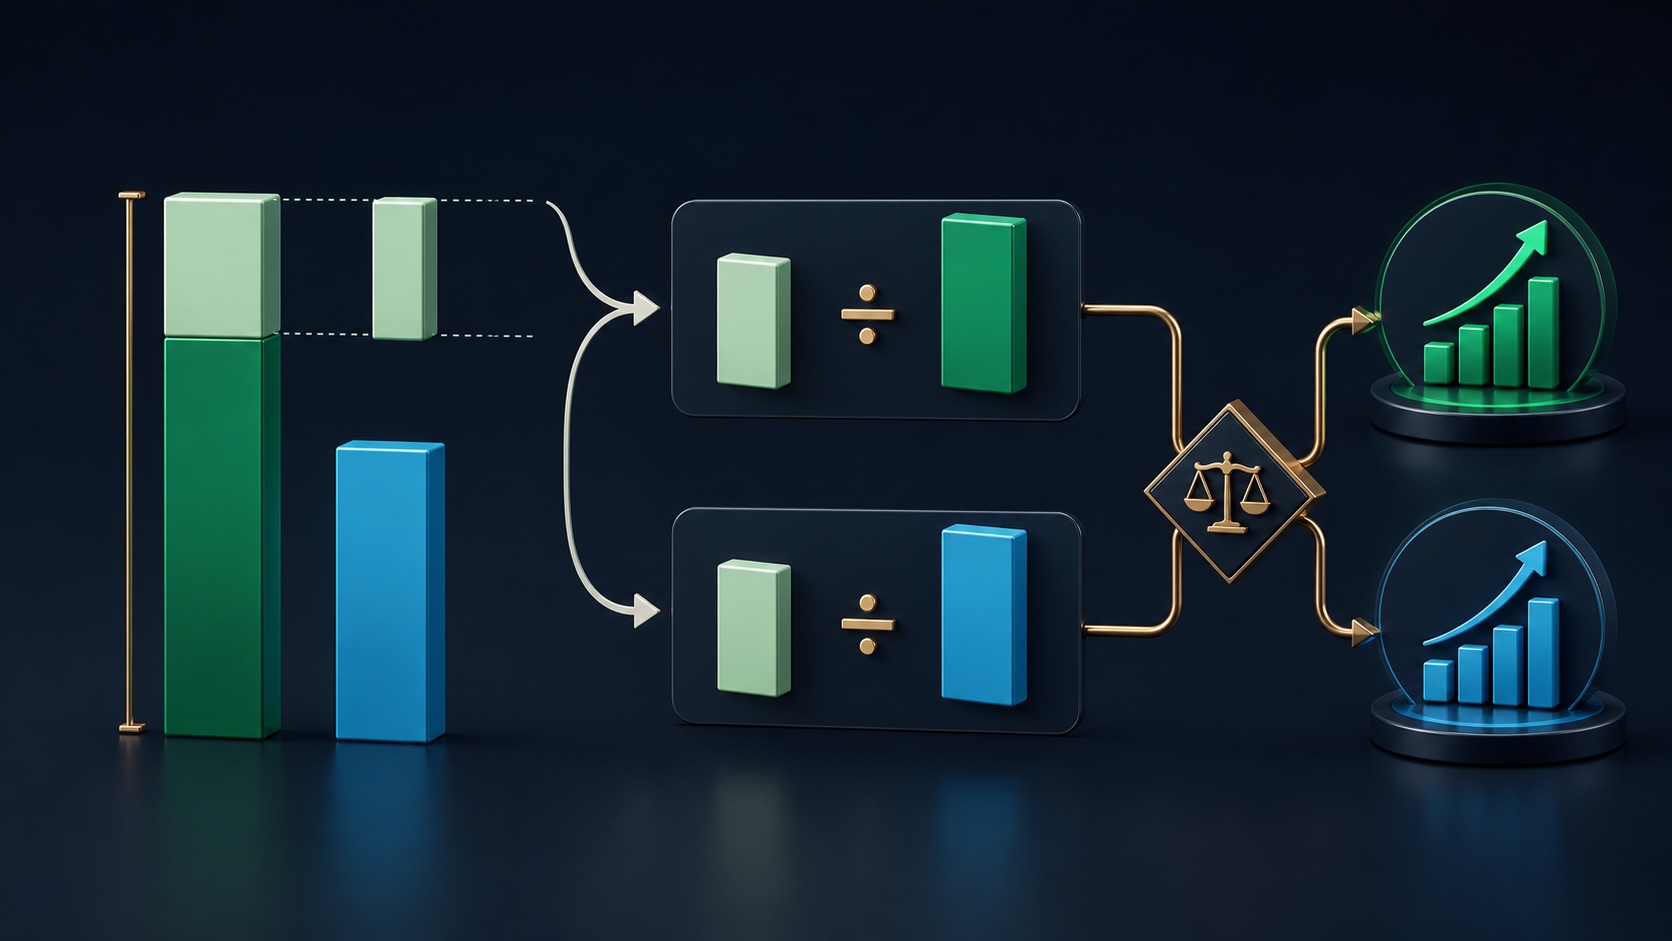
ILLUSTRATIVE WORKED EXAMPLE
Compare an illustrative $150 sale with $100 cost
PRACTICAL INTERFACE MAP
Build a denominator-safe pricing sheet
Record product or service, quantity, currency, list and net price, discounts, returns, taxes, fees, direct cost components, period, source, and finance owner.
Gross profit equals net sales price minus defined cost; margin equals gross profit divided by net sales price; markup equals gross profit divided by cost.
For target margin, price equals cost divided by one minus margin; for target markup, price equals cost multiplied by one plus markup. Then test rounding and volume.
STEP-BY-STEP LESSON
Price − cost = gross profit → divide by price or cost → labeled percentage
THE LEAD ATLAS METHOD
Lead Atlas Data can create a business-contact list for the campaign’s categories, locations, and market, but the customer should compare any list or outreach cost with its own verified margin and pricing model rather than an assumed return.See how custom list research works ↗Freeze the unit economics scope
Choose the product or service, unit, period, currency, customer or channel, list and net sales price, discounts, returns, refunds, taxes, shipping, payment fees, commissions, labor, materials, overhead treatment, and source systems. Ask finance to approve what belongs in the cost figure.
A correct formula with inconsistent inputs is still misleading. Compare like products and periods, and do not switch between list price, net revenue, standard cost, landed cost, and full cost without relabeling the calculation.
Calculate gross profit once
Gross profit for the defined unit equals net sales price minus the approved cost. In the illustrative example, a $150 net sales price minus $100 cost produces $50 gross profit. Preserve price, cost, and profit beside every percentage.
This simplified unit example is educational, not an accounting statement. Business-level gross profit may require inventory, revenue-recognition, returns, discounts, freight, labor, and other policies reviewed by finance.
Calculate margin and markup
Gross margin percentage equals gross profit divided by net sales price: $50 ÷ $150 = 33.3%. Markup percentage equals gross profit divided by cost: $50 ÷ $100 = 50%. The profit dollars are identical; the denominator creates the different rate.
Always label ‘margin’ or ‘markup’ and show the base. Saying ‘we need 50%’ without the denominator can create an unintended price and a serious planning error.
Reverse the formula for pricing
For a target gross margin, price = cost ÷ (1 − target margin). A $100 cost at 40% target margin implies $166.67 before rounding and other effects. For target markup, price = cost × (1 + target markup); 40% markup implies $140.
Check percentages as decimals, avoid a 100% margin input that makes the formula undefined, and model discounts, taxes, commissions, returns, minimum order size, and rounding before publishing a price.
Use the right percentage for the decision
Use margin when discussing profit as a share of revenue and markup when applying an uplift to cost, but follow the organization’s approved accounting and pricing conventions. Compare actual net margin with the plan after discounts, mix, returns, and cost changes.
Deliverable: unit definition, revenue and cost scope, source reconciliation, gross-profit calculation, margin and markup formulas, reverse-pricing examples, sensitivity table, rounding and discount rules, finance approval, update cadence, and owner.
THE TAKEAWAY
Label the denominator beside every percentage, use one consistent cost and revenue scope, and convert target margin or markup into price with the correct formula before approving an offer.OFFICIAL REFERENCES